Considering a five-year fix but hoping rates fall? Check the early repayment charges. Some decline, some stay flat, and others end before the fixed rate does. Flexibility matters, but so does its price
Fixing for five years? Check what it costs to leave
A five-year fix can look appealing when shorter deals cost almost the same. You get longer payment certainty, potentially at a lower rate. But what happens if rates fall and you want to switch?
Our research found at 75% LTV Nationwide’s two-year and three-year remortgage fixes at 5.12%. Its five-year fix was 4.99%, with no product fee on any option. A marginal difference.
That makes a longer fix worth considering. Your rate stays the same if general borrowing costs rise. However, it also stays the same if cheaper deals become available.
The catch... You can usually leave early, but your lender may charge an Early Repayment Charge (ERC). This typically means paying a percentage of the amount you repay. That charge could outweigh the savings from remortgaging.
Before choosing a longer fix, it therefore helps to understand the cost of leaving. Crucially, not all lenders are the same.
A familiar five-year schedule starts at 5%, then falls annually to 1%. But some charges fall more slowly, while others stay flat.
Typical — falling charges
Mortgage details are shared with the other ERC calculators on this page.
Updating estimates…
Unable to update the estimates. Please try again.
Year 1
5%ERC
£10,000.00
Year 2
4%ERC
£7,835.05
Year 3
3%ERC
£5,746.24
Year 4
2%ERC
£3,739.70
Year 5
1%ERC
£1,821.95
Estimates for repaying the full balance at the start of each year: today, then after 12, 24, 36 and 48 monthly payments. Repayment assumes a constant interest rate and no overpayments. Each year is a separate possible exit point.
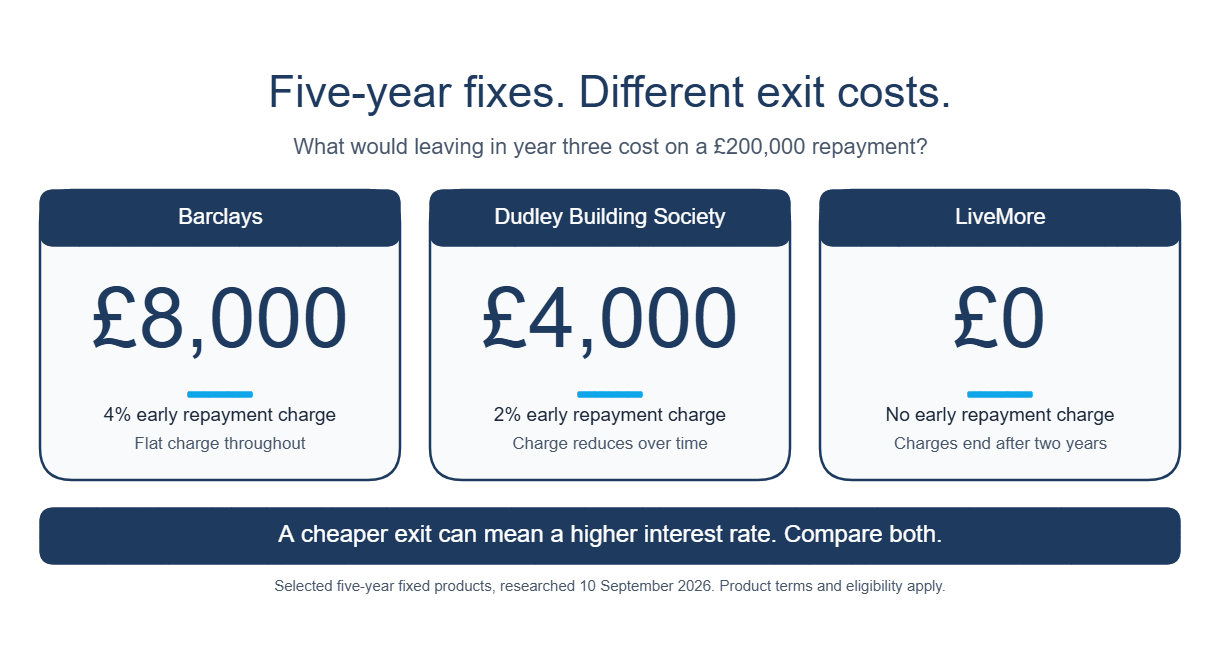
For example, Barclays’ five-year fix charges 4% throughout its fixed period.
Flat charges
Updating estimates…
Unable to update the estimates. Please try again.
Year 1
4%ERC
£8,000.00
Year 2
4%ERC
£7,835.05
Year 3
4%ERC
£7,661.66
Year 4
4%ERC
£7,479.39
Year 5
4%ERC
£7,287.80
Dudley Building Society’s schedule starts at 4%, reaching 1% for the final two years.
Low in the last two years
Updating estimates…
Unable to update the estimates. Please try again.
Year 1
4%ERC
£8,000.00
Year 2
3%ERC
£5,876.29
Year 3
2%ERC
£3,830.83
Year 4
1%ERC
£1,869.85
Year 5
1%ERC
£1,821.95
On a £200,000 repayment, those later charges would mean £8,000 versus £2,000. That difference could determine whether switching to a lower rate saves you money or makes no sense.
Some products offer a different compromise: a longer fix with a shorter tie-in. LiveMore’s five-year Flexi Fix charges 5% in year one and 4% in year two. After that, borrowers can leave without an ERC. That allows borrowers to keep their fixed rate or switch if suitable, cheaper deals appear.
No charges after year two
Updating estimates…
Unable to update the estimates. Please try again.
Year 1
5%ERC
£10,000.00
Year 2
4%ERC
£7,835.05
Year 3
0%ERC
£0.00
Year 4
0%ERC
£0.00
Year 5
0%ERC
£0.00
Removing ERCs entirely can cost considerably more, though. United Trust Bank’s Super Prime range illustrates the trade-off at 75% loan-to-value. Its five-year fix costs 5.39% with ERCs, compared with 6.59% without them. Both carry a £1,495 product fee.
You pay that higher rate from the outset, whether you eventually switch or stay. The extra interest buys flexibility; it does not guarantee a saving.
ERC-free
Updating estimates…
Unable to update the estimates. Please try again.
Year 1
0%ERC
£0.00
Year 2
0%ERC
£0.00
Year 3
0%ERC
£0.00
Year 4
0%ERC
£0.00
Year 5
0%ERC
£0.00
That is why ERCs belong alongside the rate and fees in your comparison. A lower charge may make an early remortgage worthwhile if you're confident rates will fall. No mortgage advisers can give you that confidence, from world events, budget announcements or inflation data. No one knows if rates will be up or down, or how much in 3, 4, or 5 years.
Examples reflect the research snapshot dated 10 September 2026. Rates, availability and eligibility can change. Check your mortgage illustration for the exact terms.
Get in touch
We are your online mortgage broker, offering you the convenience of applying for a mortgage online. However, we understand that sometimes you may prefer to speak with a human - phone, email or in person.
- Phone number
- 01133 205 902
- hello@cyborg.finance
- Postal address
-
31 Bradford Chamber Business Park,
New Lane, Bradford, BD4 8BX
Looking for a career in Mortgage Advice? View job openings.
We are authorised and regulated by the Financial Conduct Authority (No. 919921). The Financial Conduct Authority does not regulate most Buy to Let mortgages.
Think carefully before securing other debts against your home. Your home may be repossessed if you do not keep up repayments on your mortgage.
Our initial consultation is free. If you choose to proceed, we’ll explain any broker fees upfront before you commit.
Cyborg Finance Limited is registered in England and Wales (No. 12131863) at Bradford Chamber, New Lane, Bradford, BD4 8BX.